Cash vs. Financing: What Changes Inside Escrow at Today's Rates
Jennifer Davidson,
Owner | Office Manager | Senior Escrow Officer
Every South Orange County listing agent has heard some version of the same question lately: should my seller take the lower cash offer, or the higher financed one?
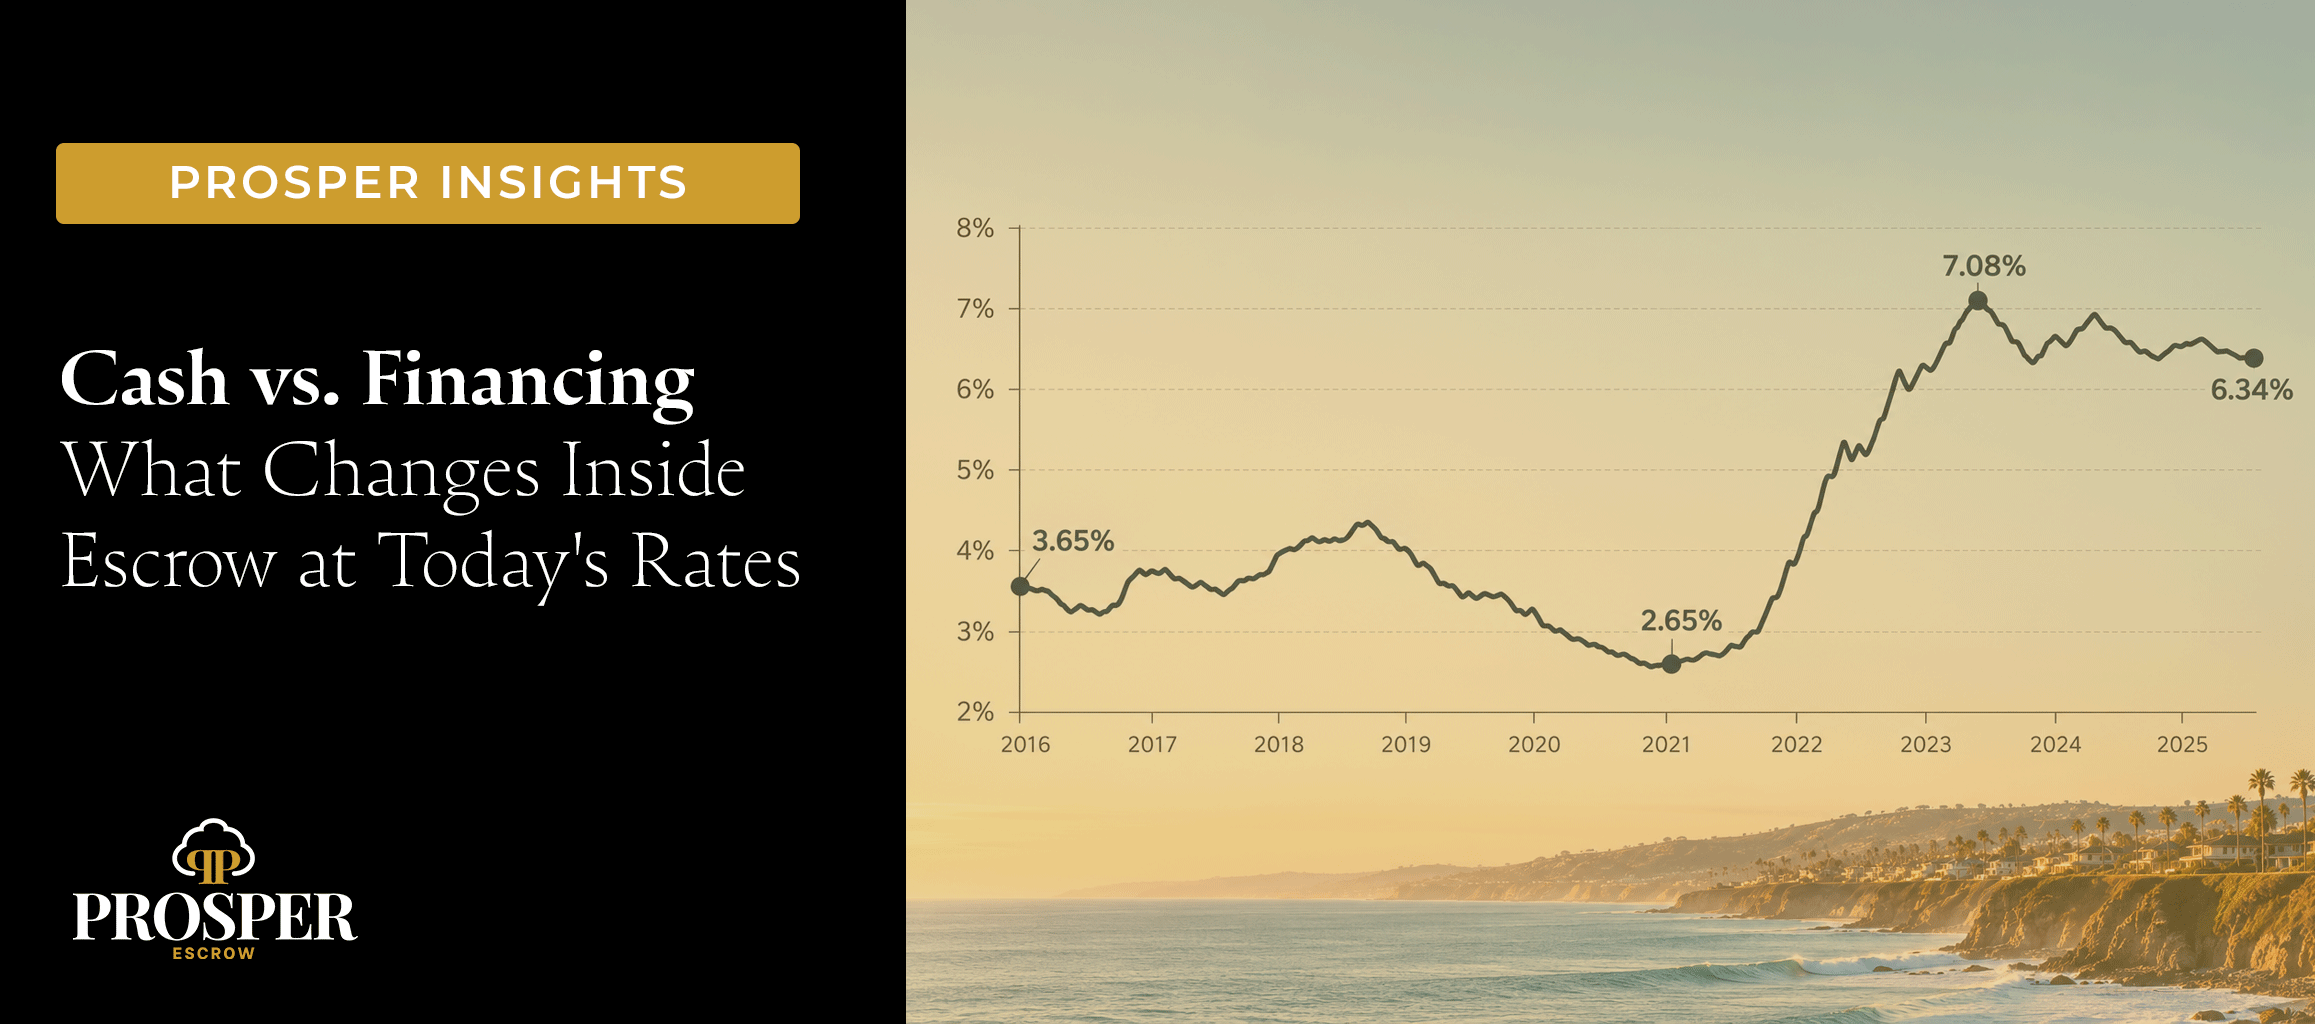
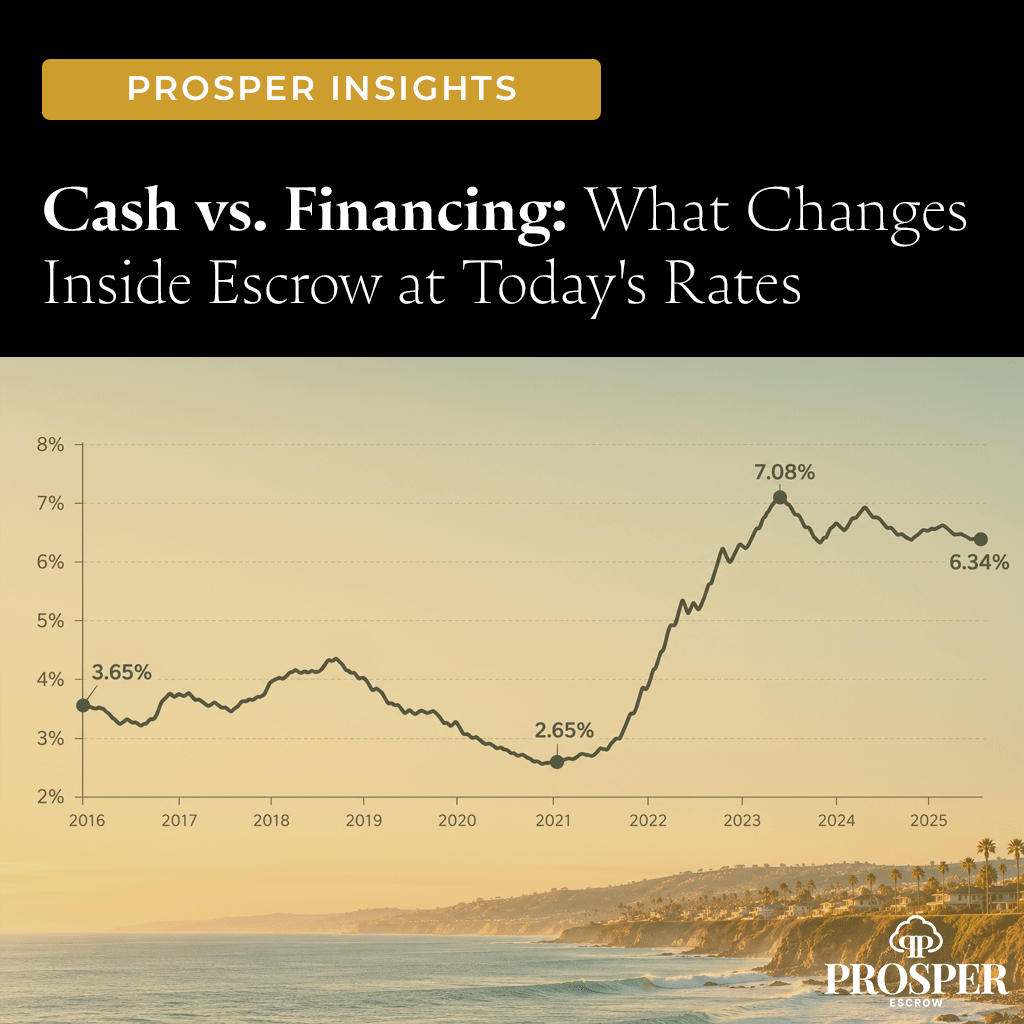
With 30-year rates sitting near 6.8%, that question matters more than it used to — not just for the sale price, but for how escrow itself unfolds.
Without a lender in the picture, several standard steps simply disappear: no loan underwriting, no lender-required appraisal, no financing contingency to negotiate around. That typically means a faster, more predictable timeline.
But cash doesn't mean no diligence. Buyers still need — and should still get — a full inspection period, title review, and often their own independent appraisal for peace of mind, even without a lender requiring one.
A financed purchase moves at the lender's pace as much as anyone else's. At today's rates, that includes:
None of this makes financed offers weaker. It just means the timeline has more dependencies outside the transaction's direct control.
A cash offer is often faster and simpler, but it isn't automatically the better one. A well-qualified, pre-underwritten financed buyer with a strong lender can close just as reliably — sometimes for a meaningfully higher price. The right comparison isn't cash versus financing in the abstract. It's this specific buyer's readiness versus that one's.
Confirm proof of funds or loan pre-approval quality before writing the timeline, not after.
A rate-lock deadline that lines up too tightly with closing adds unnecessary pressure to a financed deal.
No lender requirement doesn't mean no inspection. Encourage cash buyers to use their diligence period fully.
A strong financed buyer can outperform a weaker cash offer. Evaluate readiness, not just the label.
For financed deals, early and frequent contact with the lender prevents late-stage surprises.
At today's rates, the cash-versus-financing conversation is worth having carefully, not reflexively. The right offer isn't always the one without a lender — it's the one built on a realistic, well-supported timeline.
Subject line: Cash offer vs. financed offer: what actually changes in escrow right now
With 30-year rates near 6.8%, the gap between a cash offer and a financed one shows up in more than just price. This week's Prosper Insight covers:
The right offer is the one built on a realistic timeline, not just a label.
With 30-year rates near 6.8%, the cash-vs-financing question is coming up on nearly every South Orange County listing right now.
This week's Prosper Insight breaks down what actually changes in escrow for each — and why sellers shouldn't default to "cash always wins" without looking at buyer readiness.
#SouthOrangeCounty #EscrowTips #ProsperInsights #RealEstate #MortgageRates
💵 Cash offer or financed offer — what actually changes in escrow?
This week's Prosper Insight covers:
✔ What cash removes from the timeline
✔ What financing still requires at today's rates
✔ Why the stronger buyer isn't always the cash one
#ProsperInsights #OCRealEstate #EscrowTips #SouthOC
About the Author
Jennifer Davidson, Sr. Escrow Officer and owner of Prosper Escrow, has spent nearly two decades mastering the art of escrow. Since beginning her career in 2006, her natural talent, attention to detail, and commitment to excellence have made her a trusted leader in residential sales, refinances, probate sales, short sales, mobile home transactions, and co-ops.